
請求書処理と照合の自動化
Automation is all about maintaining the pace required in today’s fast-paced financial landscape. Invoice and reconciliation automation are two areas on which finance departments are pinning hopes to accelerate digital transformation quickly. Automating manual processes with efficient, automated systems can significantly boost productivity, reduce errors, and unlock a new level…
- 全て
- 会計
- コンプライアンス
- 法人税
- 注目記事
- 海外進出
- 個人所得税
- 給与・人事
- リスク管理
- 経営戦略
- 技術
- 未分類

加速償却の選択は、企業の長期的な財務戦略にどのような影響を与えるのでしょうか。さらに、この税制上の優遇措置によって、企業はどのような競争優位性を得ることができるのでしょうか。
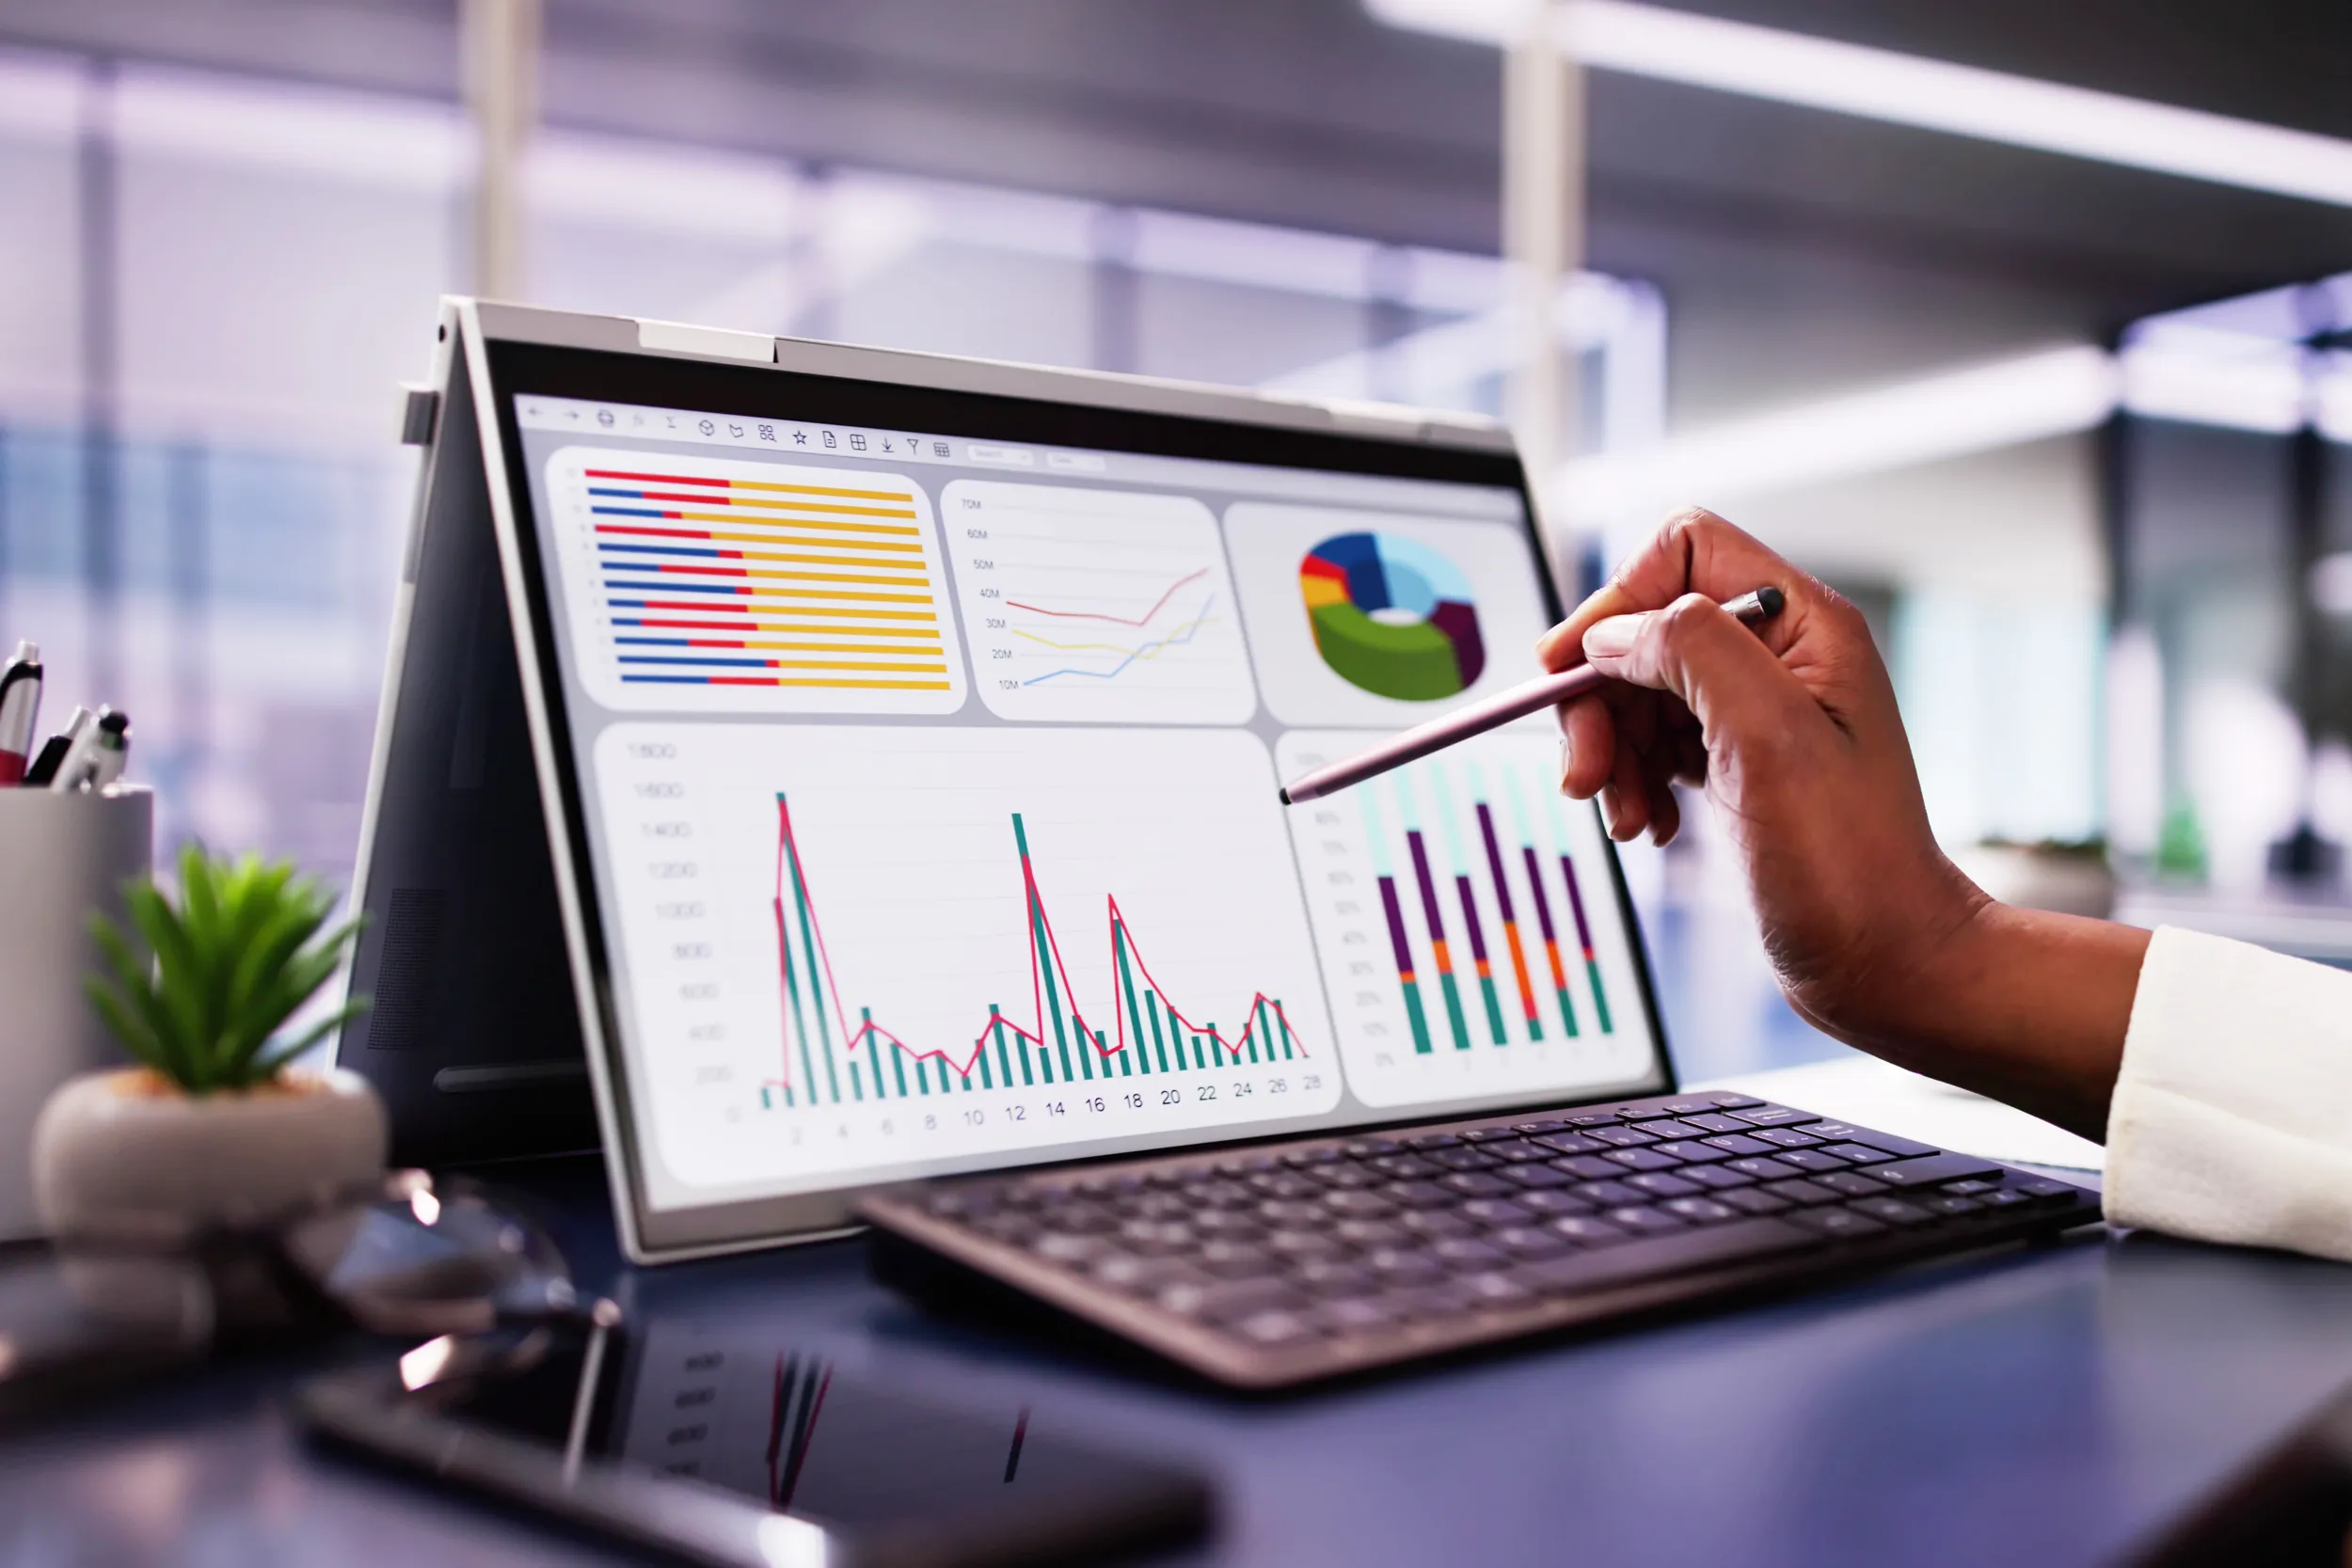


予測が難しい関税の変動にお悩みではありませんか?高度なデータ分析を活用することで、不確実性をビジネスチャンスに変え、リスクから事業を守る方法をご紹介します。

Form 941の修正申告には3年間の時効期間が設けられているため、2020年および…を対象とするERC(従業員維持税額控除)の重要性がますます高まっています。
請求書処理と照合の自動化
Automation is all about maintaining the pace required in today’s fast-paced financial landscape. Invoice and reconciliation automation are two areas on which finance departments are pinning hopes to accelerate digital transformation quickly. Automating manual processes with efficient, automated systems can significantly boost productivity, reduce errors, and unlock a new level of financial clarity.The Shift Toward Automation in FinanceMost finance teams have suffered from labor-intensive, error-prone manual processes, primarily centered around managing invoices and reconciliations, for years. Pressure to stay ahead of increasing transaction volumes and complex data needs, not to mention the speed at which decisions were being required, made it apparent that these processes needed some serious revisiting. This is where automation needs to come in, making financial operations smarter and more efficient.Invoice automation facilitates the whole process from receipt to payment, thus reducing manual entry of data and errors. It helps finance teams automatically capture invoice details, match them with purchase orders, and route for approval fully within a seamless workflow.Bank Reconciliation Automation eliminates the complexities that exist with the processes of manually matching transactions between accounts. Automating this process puts organizations in a position whereby their financial records will be accurate and up-to-date to enable their leaders to make timely, informative decisions.Key Benefits of Invoice and Reconciliation AutomationEnhanced AccuracyManual data entry tends to lead to errors in financial operations. Automated systems eliminate the human factor of error, as data capture and validation occur automatically, making sure invoices and transactions are processed accurately.Time Savings and EfficiencyThere is a huge saving of time, energy, and money in time-consuming processes like manual data entry and transaction matching. Finance professionals find ample time to focus on higher-value activities, such as analysis, forecasting, and planning.Cost SavingsAutomating operations reduces the role of human error and, hence, costs associated with mistakes, delays, and labor-intensive processes.Faster Decision-MakingAutomation ensures the processing and reconciliation of financial data in real-time. This provides business leaders with up-to-date information, speeds up decision-making and responds to financial management.Improved Compliance and Audit ReadinessAutomated systems offer more transparency and consistency in financial records. Therefore, it becomes easier to handle compliance with regulatory requirements and provide for audits. For companies to remain competitive, getting on the automation bandwagon is no longer a suggestion but a necessity. How Invoice and Reconciliation Automation Support Digital TransformationInvoice and reconciliation automation are at the forefront of the digital transformation in finance. By integrating these processes into an organization’s broader digital strategy, businesses can unlock a host of benefits:Cloud Integration: Automated systems are mostly cloud-based so that finance teams can access real-time data, even from remote locations. This also ensures scalability as the business grows and the transaction volume increases.Data Insights: The automation system captures and accumulates a mass of transactional data, which can be analyzed to gain insights about spending, supplier performance, and financial health.Improved Collaboration: Automated workflows are going to streamline communications between divisions and ensure procurement and accounts payable are all on the same page.The Path Forward: Embrace Automation for Future-Ready FinanceThe future of finance is undoubtedly digital, and two of the more critical drivers of this change are invoice and reconciliation automation.Finance teams can adopt these technologies to improve operational efficiency and form the basis on which innovation, agility, and better decision-making will be developed. The digital world that was once unpredictable has become one of predictability, where automation opens channels for new opportunities, develops growth, and allows finance teams to meet the challenges of tomorrow truly.Ready to transform finance operations? Implement invoice and reconciliation automation today and get started on the path toward a faster, safer, and future-proof financial system.
米国で従業員を雇用する際の重要なポイント
For Japanese companies entering the U.S. market, grappling with local labor laws, tax rules, and employment practices is a crucial step. Mastering these legal intricacies is key to both compliance and building a motivated, productive team. As Japanese businesses expand into the U.S. market, navigating the local labor laws, tax regulations, and employment practices becomes a pivotal challenge. Understanding the intricacies of U.S. employment law is crucial to ensuring compliance and fostering a productive workforce. The U.S. labor landscape differs significantly from Japan's, with more emphasis on flexibility in hiring and termination, varying state-specific laws, and complex taxation systems. By addressing these critical factors, Japanese businesses can avoid costly errors and integrate seamlessly into the U.S. market. 1. Tax Withholding and Reporting ObligationsOne of the first and most fundamental challenges that Japanese businesses face when hiring U.S.-based employees is the complex tax landscape. Employers in the U.S. are required to withhold federal income taxes, Social Security, and Medicare taxes from employees' wages, as mandated by the Internal Revenue Service (IRS). These withheld amounts must be reported to the IRS and remitted regularly, typically quarterly. However, U.S. taxation does not end at the federal level. States impose their income tax, payroll taxes, and other tax regulations that vary widely across jurisdictions. For instance, states like Texas and Florida do not have a state income tax, while California and New York impose relatively high-income taxes. In addition to state-level taxes, local governments in major metropolitan areas may impose additional payroll taxes. For example, New York City has its local income tax that must be withheld by employers. Navigating these state and local differences can be particularly challenging. Failing to adhere to the correct tax regulations—whether it's withholding the correct amount or filing reports on time—can lead to severe financial penalties, interest charges, and even audits. Furthermore, penalties for noncompliance can compound with the complexity of differing state tax laws. Recommendation: Japanese businesses should partner with U.S.-based tax professionals or accountants who specialize in payroll taxes. These experts can help develop a robust payroll system that accounts for both federal and state-level tax obligations. Using a sophisticated payroll software system or outsourcing payroll management can help ensure that taxes are withheld and reported correctly in every jurisdiction where employees are based. 2. Exempt vs. Non-Exempt Employee ClassificationIn the U.S., the classification of employees as “exempt” or “non-exempt” is critical for determining whether employees are entitled to overtime pay. Exempt employees are typically salaried employees who do not receive overtime pay, while non-exempt employees are typically hourly workers who are entitled to overtime pay (1.5 times their regular hourly rate) for any hours worked beyond 40 in a given workweek. The U.S. Department of Labor (DOL) provides clear guidelines for exempt vs. non-exempt classification, including specific duties tests and minimum salary thresholds. Employees earning less than this amount are generally classified as non-exempt, regardless of their job duties. Furthermore, some states have set higher salary thresholds for exempt status. Improperly classifying employees can lead to substantial financial consequences, such as back pay for unpaid overtime, interest charges, and potential lawsuits. Misclassification can also lead to reputational harm, especially if employees feel they have been wrongly denied overtime compensation. In addition, certain job duties and titles may mislead employers if an employee qualifies for exempt status when they do not. Recommendation: Japanese companies should carefully assess the job duties and compensation structure of each employee to ensure they are classified correctly under both federal and state laws. To avoid errors, companies should consult with legal or HR professionals familiar with U.S. labor laws, particularly regarding the DOL’s guidelines for overtime and exemptions. 3. Compliance with Healthcare and Employee Benefits RegulationsU.S. employee benefits laws are complex and vary significantly by state, but healthcare coverage is one of the most pressing issues for employers. Under the Affordable Care Act (ACA), employers with 50 or more full-time employees are required to provide health insurance that meets specific coverage and affordability criteria. These criteria mandate that the employer’s plan must cover at least 60% of healthcare costs (considered a “minimum essential coverage”), and the cost of coverage cannot exceed 9.78% of the employee’s annual income (in 2025) for single coverage. In addition to ACA requirements, many states impose their own healthcare mandates. For example, Massachusetts and New York require employers to provide more comprehensive healthcare coverage than federal standards. Additionally, some states like California, New Jersey, and Oregon have their own paid family leave laws and paid sick leave laws, which are mandatory for employers. In addition to healthcare, U.S. companies must offer competitive benefits packages to attract and retain talent. This often includes retirement plans (such as 401(k) plans), disability insurance, paid time off (PTO), and other supplementary benefits such as wellness programs or stock options. Failure to offer mandated benefits or to comply with state-specific requirements can result in significant penalties and employee dissatisfaction. Recommendation: Japanese businesses should develop an employee benefits strategy that is compliant with both federal and state regulations. In addition to meeting ACA requirements, employers should consult with a U.S.-based benefits consultant to design a comprehensive benefits package that attracts top talent and ensures full compliance with state-specific regulations. This may include providing additional benefits beyond healthcare, such as paid family leave or PTO, to align with regional expectations and legal obligations. 4. State-Specific Employment Laws and Paid Leave PoliciesThe U.S. lacks a federal mandate for paid vacation, but several states and cities have enacted their own paid leave laws, including paid sick leave, family leave, and other forms of paid time off. For example, California, New York, and Massachusetts have specific paid sick leave laws, which require employers to provide paid time off for employees who are ill or need to care for a family member. Similarly, several states mandate paid family leave, allowing employees to take time off for family emergencies, such as the birth of a child or caring for a sick relative. Each state has its own rules regarding the accrual of paid leave, the maximum amount of leave employees can take, and the procedures for requesting time off. These differences can pose challenges for Japanese businesses operating across multiple states, as they will need to stay current with a diverse range of leave policies and adapt their internal practices accordingly. Moreover, some states have additional regulations on other benefits, such…
新会社設立における4つの事業形態
政府への事業登録時には、事業主がどの事業形態で事業を行うかを選択します。主な事業形態には、個人事業主、パートナーシップ、LLC(有限責任会社)、法人があります。最適な事業形態はケースによって異なり、それぞれにメリットとデメリットがあります。
シンプルな仕組みで、ビジネスを不正から守る
Stop fraud and errors before they start with segregation of duties, a simple, powerful strategy to protect your business from unnecessary risk. Fraud, errors, and mismanagement can happen in any business—but what if there was a simple, powerful tool to stop it before it starts? Segregation of Duties (SOD) is one of the best-kept secrets for protecting your organization from financial fraud and risk. It’s a simple control that could be the difference between a secure, thriving business and one exposed to costly mistakes.In fact, SOD could be the first line of defense against fraud, unauthorized transactions, and compliance issues in your organization’s most critical processes—cash disbursements, procurement, and payroll. And the best part? It’s easier to implement than you think.What is Segregation of Duties, and Why Should You Care?At its core, Segregation of Duties means spreading out responsibilities across multiple people so that no one person has total control over any single financial transaction. Why? Because when one person controls the entire process, from start to finish, the door is wide open for fraud, mistakes, or even simple oversights.Imagine this scenario: One employee is responsible for approving and processing payments. This means they could easily approve an invoice for services never rendered—or divert funds to a personal account—and no one would notice until it’s too late. By splitting these responsibilities between two or more people, you create a built-in safety net that makes fraud far more difficult to pull off. The beauty of SOD is that it doesn’t require complex software or expensive systems—it’s just about ensuring no one person is a “gatekeeper” for all aspects of a transaction. What if a simple, cost-effective tool could protect your business from fraud, costly mistakes, and compliance nightmares? Segregation of Duties (SOD) is the secret weapon that keeps your financial processes secure—by splitting key responsibilities, it turns your weakest link into your strongest defense against risk. Don’t wait for a crisis—make SOD your first line of defense today! What Are the Pitfalls Companies Must Watch Out For?Here are the top 3 pitfalls companies often overlook when designing or maintaining their internal controls. Avoiding these mistakes will ensure your SOD strategy is robust, and your business remains secure. Lack of Separation in Key ProcessesOne of the biggest mistakes companies make is failing to properly separate duties in high-risk areas like cash disbursements, procurement, and payroll. For instance, if the same person is both approving invoices and processing payments, they essentially have unchecked power over the entire process. This creates a golden opportunity for fraud or errors to go unnoticed. Inadequate Monitoring and AuditingEven if your SOD framework is well-structured, if it isn’t monitored regularly, the risk of fraud and errors remains. Without consistent reviews or audits, employees may feel emboldened to bypass controls or take shortcuts, knowing they aren’t being checked frequently enough. Overlooking the Impact of New Technologies or Staffing ChangesAs businesses grow, hire new staff, or implement new technologies, the way processes are handled may shift, creating new vulnerabilities. For instance, a new employee with access to sensitive systems might unintentionally violate SOD policies, or new software might inadvertently consolidate too many duties under a single role. How to Identify Weaknesses in Your SOD Framework?An Interactive SOD Matrix is a powerful tool for identifying where your internal controls might be weak and how to address them. This matrix helps you: Spot conflicts in roles and responsibilities. Does one person have too much control over a financial process? The matrix will flag it.Suggest solutions for compensating controls. For example, it might recommend requiring dual approvals for high-value payments or setting up automated checks for expense claims. Ask the right questions to keep your controls relevant. Is your business growing? Have you adopted new technologies? Are new staff members handling sensitive roles? The matrix guides you through it all, helping you stay ahead of emerging risks. By using this tool, you’ll have a clear, actionable roadmap to make your internal controls as strong as possible—before problems even have a chance to arise. Don’t Wait for a Fraud Crisis—Act NowThe risks of not implementing proper SOD are real, and they’re growing every day. Fraud, financial mismanagement, and compliance violations don’t just happen to other people, they can happen to anyone. It’s not just about preventing fraud—it’s about setting your business up for long-term success and protecting your bottom line. The earlier you implement SOD, the sooner you can sleep soundly knowing that your financial processes are secure. If you'd like to discuss your findings further, reach out to us—we’re here to help your organization implement SOD and manage risk strategically.
米国でサイバーセキュリティ人材を採用する際に押さえておきたい5つのポイント
米国でサイバーセキュリティ人材を採用する際の5つのポイント 米国でサイバーセキュリティ人材を確保することは、日本企業にとって重要な課題です。適切な専門人材を採用するための5つのポイントと、企業のデータを守るうえでアウトソーシングが有効な選択肢となるのかを解説します。 サイバー攻撃がますます高度化・頻発する中、デジタル資産の保護は世界中の企業にとって最も重要な課題の一つとなっています。米国で事業を展開する日本企業にとって、この課題は特に重要です。 米国はサイバー攻撃の主要な標的の一つであり、脅威が急速に変化しているだけでなく、規制環境も常に変化しています。さらに、カリフォルニア州消費者プライバシー法(CCPA)などのデータプライバシー規制や、HIPAAなどの業界固有の基準も加わり、対応はより複雑になっています。 米国で事業を成長させるためには、機密データを保護し、顧客からの信頼を維持するとともに、法令や規制を遵守するための強固なサイバーセキュリティ体制が不可欠です。その重要な要素の一つが、適切なサイバーセキュリティ人材の採用です。 米国で事業を展開する日本企業が、サイバーセキュリティ専門人材を採用する際に知っておくべき5つのポイントをご紹介します。 1. 必要なスキルを明確にする サイバーセキュリティは幅広い分野であり、さまざまな専門領域があります。適切な人材を採用するためには、まず自社に必要なスキルや役割を明確にすることが重要です。 企業にとって重要となる職種には、リアルタイムで脅威を監視・特定するセキュリティアナリスト、データ漏えいやセキュリティインシデントへの対応・被害軽減を担うインシデント対応担当者、攻撃者に悪用される前にシステムの脆弱性を検証するペネトレーションテスターなどがあります。 さらに、強固なセキュリティインフラを設計・維持するセキュリティエンジニアや、必要な法令・規制基準への準拠を管理するコンプライアンス担当者も重要です。 自社のセキュリティ上の優先事項を明確にし、米国の規制要件と照らし合わせることが重要です。GDPRへの対応やネットワークセキュリティの確保など、自社が特に脆弱な分野を把握することで、採用の優先順位を決め、求める人材像を明確にできます。 2. サイバーセキュリティ人材は高い需要がある サイバー攻撃の頻度と巧妙さが増す中、サイバーセキュリティの専門人材に対する需要はかつてないほど高まっています。 米国では人材獲得競争が激しく、適切な人材の採用・定着に苦労する企業も少なくありません。米国で事業を展開する日本企業にとって、この競争はさらに厳しいものとなる可能性があります。 米国のサイバーセキュリティ人材市場は競争が激しいだけでなく、技術や攻撃手法も絶えず変化しています。 優秀な人材を獲得するためには、米国の業界水準に見合った競争力のある給与や福利厚生を提供することが重要です。また、キャリア開発の機会を提供することで、従業員が進化するサイバー脅威に対応するための知識やスキルを継続的に高められます。 さらに、働きやすい環境を整えることは、人材の定着にもつながります。給与だけでなく、成長の機会や良好な職場環境を提供することで、競争の激しい人材市場において自社を差別化できます。 3. 経験だけでなく、将来性にも注目する サイバーセキュリティ人材を採用する際、経験年数は重要な要素ですが、それだけが判断基準ではありません。 サイバーセキュリティを取り巻く環境は常に変化しており、多くの専門家が独学、資格取得、セキュリティコミュニティへの参加などを通じてスキルを身につけています。そのため、豊富な経験を持つ人材だけでなく、学習意欲や成長の可能性を持つ人材を採用することも有効です。 日本企業にとって、このような採用方針は人材の選択肢を広げることにつながります。従来とは異なる経歴を持つ人材から、新たな視点や問題解決能力を取り入れることもできます。 米国のサイバーセキュリティ専門家には、ソフトウェアエンジニアリング、IT、数学などをバックグラウンドに持つ人材も多くいます。変化に柔軟に対応し、迅速に学習し、セキュリティ上の課題に革新的なアプローチで取り組める人材は、企業にとって大きな価値となります。 4. ソフトスキルを重視する ― 文化への適応力が重要 技術的なスキルは不可欠ですが、コミュニケーション能力や文化への適応力といったソフトスキルも同様に重要です。 米国で事業を展開する日本企業にとって、技術面だけでなく組織面からもセキュリティに対応できる人材を採用することが重要です。 複雑なセキュリティ上の問題を、専門知識を持たない関係者にも分かりやすく説明するためには、優れたコミュニケーション能力が求められます。セキュリティチームには、リスクやインシデント、予防策について、誰にでも理解できる言葉で説明する能力が必要です。 また、日本の企業文化と、より協働的で多様性のある米国の職場環境との違いを理解し、適応できることも重要です。こうした文化的な違いを理解するサイバーセキュリティ人材であれば、チームに円滑に溶け込み、グローバルなセキュリティ戦略との整合性を保つうえでも貢献できます。 特に、非技術部門を含むさまざまな部門と連携できる能力は、組織全体にセキュリティ意識を浸透させるうえで不可欠です。 5. 継続的なトレーニングと資格取得に投資する サイバーセキュリティは常に進化する分野であり、新たな脅威に対応するためには継続的な学習が欠かせません。 強固なセキュリティチームを維持するには、研修や専門能力開発の機会を提供することが重要です。米国では、CISSP(Certified Information Systems Security Professional)、CEH(Certified Ethical Hacker)、CompTIA Security+などの資格が広く認知されており、サイバーセキュリティチームの能力向上にも役立ちます。 日本企業にとって、継続的な教育やトレーニングを支援することは、最新のセキュリティ技術や規制に対応できる体制づくりにつながります。また、従業員の成長を支援する姿勢を示すことで、従業員満足度や定着率の向上にもつながります。 定期的なトレーニングによって、次々と現れるサイバー脅威への対応力を高め、組織全体のレジリエンスを強化できます。 サイバーセキュリティのアウトソーシングは、コストだけの問題ではない サイバーセキュリティのアウトソーシングは、単なるコスト削減ではありません。重要なのは、サイバー攻撃に対抗できる適切な専門家を確保することです。 日本企業はサイバーセキュリティをアウトソーシングすべきか? 米国ではサイバーセキュリティ人材の採用競争が激しいため、多くの企業が代替策または補完策としてアウトソーシングを検討しています。 米国で事業を展開する日本企業にとって、アウトソーシングにはいくつかの大きなメリットがあります。 主なメリットの一つが、専門的な知識やノウハウへのアクセスです。マネージド・セキュリティ・サービス・プロバイダー(MSSP)には、最新の脅威、ツール、ベストプラクティスに精通したサイバーセキュリティの専門家が在籍しています。 MSSPに業務を委託することで、24時間365日の監視、インシデント対応、脅威管理などを受けられます。自社で専門チームを構築・維持する必要がないため、日本企業にとっては、強固なセキュリティ体制を確保しながら運用コストを抑えられる、費用対効果の高い選択肢となる可能性があります。 また、アウトソーシングには拡張性と柔軟性というメリットもあります。事業の成長や新たなセキュリティ上の課題に応じて、委託先がサービス内容を迅速に調整できます。 この柔軟性は、まだ専任のサイバーセキュリティ担当者を置く必要がない一方で、高度なセキュリティ対策を必要とする中小企業にとって特に有効です。 一方で、サイバーセキュリティのアウトソーシングには課題もあります。大きな懸念の一つは、セキュリティ運用を直接管理できなくなる可能性があることです。アウトソーシングを利用する場合、機密性の高い企業データやシステムを第三者に委託することになります。そのため、信頼性、セキュリティ、実績の面で十分な実績を持つプロバイダーを選ぶことが不可欠です。
EC向け総合ソリューション
The integration of Shopify, NetSuite, and Avalara brings about transformative benefits, empowering businesses to compete well in the e-commerce space. Businesses operating in today's evolving e-commerce marketplace are facing rising expectations related to operational efficiency, accuracy in tax compliance, and the need for outstanding customer experience. The task? Integrating front-end sales applications with back-end systems, including tax solutions, in ways that are seamless and scalable. We have dedicated ourselves to the integration of NetSuite, Avalara, and Shopify into a robust commerce ecosystem from end to end.This integration turns fragmented processes into a unified workflow, where businesses can automate operations, reduce errors, and focus on growth. Here's how this trio of industry-leading platforms comes together to deliver a comprehensive solution.Shopify: Powering Your Front-End SalesShopify is one of the cornerstones of e-commerce for businesses of all sizes. It gives companies a friendly platform on which to create, manage, and scale their online stores. Besides its tools for multi-channel sales, Shopify integrates seamlessly with Avalara and NetSuite to transform it from just a storefront into a critical component of an interconnected commerce system. Its product listing capabilities allow for streamlined catalog management with efficient order processing. With features like multi-channel selling, businesses can reach more customers through websites, marketplaces, and social media. Real-time order, inventory, and shipping status updates further increase transparency and trust among customers. While Shopify does an excellent job of handling front-end operations, the real potential is unleashed when it is used with powerful back-end systems.NetSuite: The Operational BackboneNetSuite is the cloud-based ERP solution that underpins your e-commerce operations. By centralizing key business workflows, NetSuite ensures seamless front-end sales and back-end processes. Orders from Shopify are instantly synchronized with NetSuite, allowing real-time tracking and efficient fulfillment. Its inventory optimization tools provide businesses with a unified view of stock levels across multiple locations and channels, preventing stockouts and overstocking. In addition, NetSuite has a comprehensive financial management system that captures all Shopify transactions and ensures accurate reporting and compliance with financial regulations. Customer and sales data are consolidated, offering actionable insights for marketing strategies and business decisions. The scalability of the platform ensures that businesses adapt and grow with complexity in operations.Avalara: Simplifying Tax ComplianceTax compliance can be a very challenging and time-consuming issue, especially for businesses operating in multiple jurisdictions. Avalara has stepped up as the industry leader to automate tax calculations, filing, and reporting, which simplifies this critical aspect of commerce. It gets the tax rate right at checkout, based on the regulations of a particular location, and jurisdictional compliance through updates in changing tax laws. Avalara also automatically prepares and files tax returns so that businesses are relieved of the burden of administrative work and reduced from the risk of penalties. Moreover, Avalara's detailed record-keeping feature makes auditing less stressful and more transparent. By integrating Avalara into Shopify and NetSuite, businesses achieve seamless tax compliance with no manual intervention and errors.How These Platforms Work TogetherWith Shopify, NetSuite, and Avalara, the whole system comes together in a seamless, end-to-end commerce process. Here's how it works in action:Customer Purchase: A customer orders from Shopify. Avalara computes the correct taxes, and payment is made.Order Sync: All order information, including customer details, SKUs, and tax split, is automatically synced to NetSuite.Fulfillment and Shipping: NetSuite takes care of inventory updates, picking, packing, and shipping with real-time updates sent back to Shopify.Tax Compliance: Avalara gathers tax data from the order, hence easy filing and complianceFinancial Integration: All details of a transaction are pulled into NetSuite, where they are consolidated for reporting and strategic analysisThe process, as above, cuts out duplication, minimizes errors, and attains unmatched operational efficiency. Contact us today to learn how we can help you implement and optimize this integration for your unique business needs. Let us take the complexity out of commerce so that you can focus on growing your business! Why Choose This Integration?The integration of Shopify, NetSuite, and Avalara brings about transformative benefits, empowering businesses to compete well in the e-commerce space. Automated tasks like data entry, reconciliation, and tax calculation enable companies to streamline their operations and drive growth. It also gives businesses unparalleled scalability in terms of their ability to handle greater transaction volumes and complex workflows. Customer satisfaction is higher due to faster order processing, accurate updates, and timely fulfillment, while Avalara ensures ongoing tax compliance amid changing regulations. Another advantage is that consolidated data from all three platforms helps provide deep insights into sales trends, customer behavior, and overall financial performance. This, in turn, positions businesses well to adapt to market demands, overcome operational challenges, and move towards sustainable growth. Partner for Your Integration NeedsACCO Venture Group understands that multiple systems are brought together to create a cohesive commerce solution. Our expertise in NetSuite, Avalara, and Shopify integration helps the business operate smoothly, scale with ease, and ensure tax compliance.
グループ会社間貸付に関する外貨税務ルール
Struggling with FX tax on intercompany loans? Learn how Section 987 simplifies reporting, cuts compliance burdens, and unlocks opportunities for U.S. multinationals. The introduction of the new Section 987 regulations has reshaped how U.S. multinational corporations (MNCs) handle the tax treatment of foreign currency gains and losses, particularly those arising from intercompany loans between U.S. parent companies and their foreign branches. Prior to the regulations, the treatment of such foreign exchange (FX) gains and losses was often a gray area, leading to confusion and inconsistency in tax reporting. The new rules, designed to reduce these complexities, aim to bring clarity to the tax treatment of these transactions, but also introduce some strategic considerations for businesses engaged in intercompany lending.This article focuses on how the new Section 987 regulations impact the taxation of FX gains and losses on intercompany loans, especially as they pertain to the branch-level currency election and other key provisions that apply to foreign branches. By diving deeper into the treatment of FX fluctuations on intercompany loans, businesses can better navigate the complexities and take advantage of the regulatory changes. The Role of Intercompany Loans in Cross-Border OperationsIntercompany loans are commonly used by U.S. multinationals to finance the operations of their foreign branches or subsidiaries. These loans can be used for working capital, capital expenditures, or other business needs. When a U.S. parent lends to its foreign branch, the loan is typically denominated in the local currency of the foreign branch, which could be the euro, yen, pound, or any other foreign currency.The primary issue with intercompany loans arises from fluctuations in foreign currency exchange rates between the time the loan is issued and when it is repaid or adjusted, which can lead to significant FX gains or losses on the loan balance. Under previous tax rules, these fluctuations had to be meticulously tracked and reported for tax purposes. However, the U.S. tax treatment of these FX gains and losses has been streamlined with the introduction of the Section 987 regulations, including the branch-level currency election and other provisions designed to address FX volatility in a more consistent and efficient manner.Impact of Section 987 Regulations on Intercompany LoansThe new regulations impose a more systematic approach to the treatment of foreign currency gains and losses arising from intercompany loans made to foreign branches. The main goal of the Section 987 regulations is to simplify and clarify how these FX fluctuations should be treated for U.S. tax purposes.Under the old rules, U.S. multinationals were required to track each individual transaction between the parent company and its foreign branches, translating each loan payment or adjustment based on the exchange rate in effect at the time of the transaction. This could result in a multitude of FX gains and losses being recognized over the life of the loan, making tax compliance particularly cumbersome.With the new Section 987 regulations, the rules governing intercompany loans are aligned more closely with the overall treatment of branch-level income. One of the most significant changes is the ability for U.S. taxpayers to elect the functional currency of the branch (e.g., the euro for a branch in France) for tax purposes, which allows them to treat the FX movements on intercompany loans in a simplified manner.How Does the Branch-Level Currency Election Help Manage FX Volatility?The branch-level currency election under Section 987 allows a U.S. parent company to treat the functional currency of its foreign branch for tax purposes. This means the branch’s income, expenses, and intercompany transactions are reported in its functional currency, rather than converting everything to U.S. dollars.For example, GreenEnergy Inc., a U.S.-based multinational, has a branch in Tokyo. The company has made an intercompany loan of ¥1 billion (1 billion Japanese yen) to its Japanese branch to support local operations. The exchange rate between the yen and the U.S. dollar fluctuates from ¥1 = $0.0067 in January to ¥1 = $0.0062 in October due to economic shifts and changes in monetary policy from the Bank of Japan.Under the previous tax rules, GreenEnergy would have to track these fluctuations and recognize FX gains or losses every time there is a change in the exchange rate. For instance, if the exchange rate moves from ¥1 = $0.0067 to ¥1 = $0.0062, GreenEnergy would recognize a FX loss on the loan repayment or balance adjustment.However, with the branch-level currency election, GreenEnergy can choose to use yen as the functional currency for its Tokyo branch. Instead of recalculating the FX impact on each individual loan repayment, GreenEnergy can report all transactions in yen, and the net result (after translating the branch’s income and expenses into U.S. dollars at the average yen-to-dollar exchange rate for the year) is what will be taxed. For example, if the average exchange rate is ¥1 = $0.0065, GreenEnergy will aggregate the financial performance of its Tokyo branch in yen and translate that into U.S. dollars using the average rate, thereby reducing the administrative burden and smoothing out the FX fluctuations on the loan. With smart tax strategies in place, U.S. multinationals can transform foreign exchange volatility into a powerful lever for global expansion, all while simplifying financial reporting. This opens up exciting new opportunities for strategic tax planning and currency risk management, allowing companies to stand out and seize the key to success in the fast-changing global market. What Key Considerations Should Multinationals Weigh in FX Planning?While the branch-level currency election simplifies the tax treatment of intercompany loans, it can affect several key areas of a company’s operations and financial management. Businesses should carefully consider the strategic implications of making this election.One primary consideration is how the election impacts loan structuring and currency risk management. For companies that frequently engage in intercompany lending, the decision to elect a branch's functional currency can have lasting consequences on how currency risks are managed across the organization. The election influences not just the tax treatment of intercompany loans, but also the company’s approach to hedging and mitigating foreign exchange risks. Over time, the selection of a functional currency at the branch level could lead to significant differences in how currency fluctuations are reported and managed from both a tax and operational perspective, potentially introducing new risks or opportunities depending on the volatility of the selected currency.Another critical aspect to consider is foreign tax credit planning. U.S. multinationals often…
IC-DISCとFDIIの選択方法
Not sure whether IC-DISC or FDII is the best choice for your business? This article breaks down the key differences to help U.S. exporters make an informed decision. U.S. exporters aiming to optimize their tax position should carefully assess which export tax incentive—IC-DISC or FDII—best fits their unique business needs. Both regimes offer distinct advantages, but the right choice hinges on the nature of the business's activities and its foreign market strategy. Making the right decision can significantly reduce tax liabilities and increase competitiveness in global markets. IC-DISC ConsiderationsThe Interest Charge Domestic International Sales Corporation (IC-DISC) regime is a tried-and-true tax incentive specifically designed for U.S. businesses that export goods—whether those goods are manufactured, produced, or grown within the United States. The IC-DISC offers two primary benefits: tax deferral and conversion of ordinary income into qualified dividends, which are taxed at a lower rate. Under the IC-DISC structure, businesses can create a separate corporate entity that functions as a commission agent. This entity earns a commission based on a percentage of the business’s export revenue, allowing the parent company to reduce its taxable income. While this creates a valuable tax-saving opportunity, the structure involves certain complexities and costs that businesses must weigh before opting in. The IC-DISC requires the establishment of a separate corporate entity, which incurs setup costs, as well as ongoing operational expenses. These include maintaining separate books, filing separate tax returns, and ensuring compliance with specific regulations for IC-DISCs. This added complexity may make the IC-DISC better suited for larger businesses or those with significant export activity that can absorb the additional administrative burden. When determining the commission amount the IC-DISC will receive, there are three methods to choose from. 4% Gross Receipts Method: The IC-DISC earns a fixed commission of 4% of the gross export receipts. 50-50 Combined Taxable Income Method: The commission is based on 50% of the combined taxable income of the parent company and the IC-DISC. Section 482 Method (Arm’s Length Pricing): This method, which adheres to transfer pricing rules, is used less frequently but allows for a commission to be set at an arm’s length rate. The ability to convert income from regular sales into qualified dividend income means the company could benefit from preferential tax rates on dividends. However, businesses must also consider the complexity of maintaining compliance with both U.S. tax laws and regulations governing IC-DISCs, which can sometimes outweigh the benefits, depending on the business size and structure. FDII ConsiderationsOn the other hand, the Foreign-Derived Intangible Income (FDII) regime provides an alternative tax benefit that is more straightforward and accessible for many U.S. companies. Unlike the IC-DISC, FDII does not require the establishment of a separate entity. Instead, it provides a deduction to companies that earn income from foreign-derived sales or services. For qualifying businesses, this means they can take a deduction of 37.5% of their foreign-derived intangible income, effectively lowering the tax rate on this income from the standard corporate rate of 21% to just 13.125%. FDII applies specifically to intangible assets such as intellectual property, patents, trademarks, software, and similar products. As such, it is particularly advantageous for businesses in the technology, software, and service sectors that export intangible goods or services to foreign markets. For example, a software company that sells licenses to foreign customers or a firm that provides consulting services abroad could benefit from this deduction. However, one notable caveat is that the FDII deduction will decrease after 2025. The deduction rate will be lowered to 21.875%, resulting in an effective tax rate of 16.4% for qualifying income. While still attractive, this reduction is something that businesses need to factor into long-term tax planning. The right tax incentive could be your business’s competitive edge—find out which one gives you the best advantage in global markets. Key Factors in Deciding Between IC-DISC and FDIIWhen choosing between the IC-DISC and FDII regimes, businesses must consider several factors, such as the type of products or services they export, the size and structure of their operations, and their future growth plans. Here are some key points to guide the decision-making process. Nature of Products or ServicesIC-DISC is particularly beneficial for businesses that manufacture, grow, or produce tangible goods in the U.S. and export them to foreign markets, making it a natural fit for industries like manufacturing, agriculture, and food production. In contrast, FDII is more suited for businesses that primarily export intangible assets or services, such as software, intellectual property, or consulting, which makes it an ideal choice for tech companies, service providers, or intellectual property-based businesses. Complexity and CostsWhile the IC-DISC offers more substantial tax benefits through dividend conversions, it requires a separate legal entity, which comes with additional setup and ongoing compliance costs. This complexity might be better suited for larger businesses with significant export activities and the ability to absorb the administrative burden. On the other hand, FDII is simpler to implement as it doesn’t require a separate entity, making it more cost-effective for businesses with a focus on foreign sales of services or intangible goods. Future Tax ConsiderationsThe IC-DISC allows for deferral of income and benefits from reduced tax rates on dividends, which can be an attractive strategy for long-term tax savings. However, its complexities might limit its usefulness for smaller exporters or those with limited export operations. For companies anticipating higher exports of intangible products or services, the FDII deduction provides a more direct, easier-to-implement solution. While the deduction rate will drop slightly after 2025, it still offers significant savings relative to standard corporate tax rates. Industry-Specific ConsiderationsThe IC-DISC may be particularly advantageous for industries such as manufacturing, agriculture, and wholesale trade, where tangible goods are being exported to foreign markets. The FDII tax break is especially beneficial for companies in the technology, software, and consulting industries where services or intellectual property are being exported. Be sure to keep up to date with any legislative changes and ensure that your business complies with the latest requirements to maximize the potential tax savings from these export incentives. If your business is already exporting products to international markets or you're evaluating the tax considerations of doing so, now is the perfect opportunity to act. Feel free to reach out to us.
繰延税金項目が財務諸表に与える影響
Conceded charge items are essential in the precision and straightforwardness of budget summaries. They emerge from contrasts between bookkeeping principles and expense guidelines, influencing an organization's accounted-for money and duty commitments. Appropriately obtaining and overseeing conceded charge items can assist organizations with enhancing monetary announcement and consent to administrative prerequisites.What Are Deferred Tax Items?Deferred tax items are temporary differences between the income reported on financial statements and the taxable income reported to tax authorities. These differences can lead to deferred tax assets (DTAs) or tax liabilities (DTLs).Types of Deferred Tax ItemsDeferred Tax Assets (DTAs): This occurs when taxable income is higher than book income, resulting in higher tax payments than the expenses recognized on financial statements.Example: A business accrues expenses for accounting purposes but deducts them for tax purposes in a later period.Deferred Tax Liabilities (DTLs): Arise when book income exceeds taxable income, creating a future obligation to pay taxes.Example: Accelerated depreciation methods are used for tax reporting, not financial reporting.Understanding these items is crucial for accurate financial analysis and decision-making.Why Are Deferred Tax Items Important?Deferred tax items significantly impact your company’s financial statements and decision-making processes. Here’s why they matter:Transparency in Financial ReportingThis explains that deferred tax items allow statements to depict a correct picture of a company’s taxes over a given period of time. These current ratios enable stakeholders to assess the business entity's solvency.Impact on EarningsMost changes in deferred taxes influence earnings; therefore, their statements are significant. The inability to report these things twists the framework, which might affect the financial backer's certainty and market viewpoint.Tax Planning OpportunitiesAnalyzing deferred tax items allows businesses to strategize tax-saving opportunities. For instance, identifying recurring DTAs may highlight areas for operational improvements or tax credit optimizations. Regular reviews and using tax software ensure accurate management of deferred tax items. Deferred Tax Assets: Creation and UtilizationDTAs represent future tax reductions. They are created when expenses are recognized in financial statements before they are deductible for tax purposes.Examples of DTAsNet Operating Losses (NOLs): Businesses experiencing losses can carry these forward to offset future taxable income, creating a DTA.Warranty Provisions: When a company accrued warranty expenses for financial reporting but only deducts them for taxes when incurred.Utilization of DTAsDTAs reduce future tax liabilities. However, their realization depends on the company's ability to generate sufficient taxable income. Businesses must evaluate DTAs regularly to determine whether they are still recoverable.Deferred Tax Items and the Income StatementDeferred tax items influence two key components of the income statement:Provision for Income Taxes: This is both the current tax provision and the provision for the future. Accounting helps the company to present accurate figures of its financial situation.Net Income: Movements in deferred tax provisions are adjusted to the income statement, hence a direct base on net income, which has a resulting effect on the various profitability indices used by investors and analysts.Balance Sheet Implications of Deferred Tax ItemsDeferred tax assets and liabilities appear on the balance sheet under non-current assets or liabilities. Legitimate characterization is fundamental for accurately portraying an organization's monetary position.Deferred Tax Items and Cash FlowWhile conceded charge things don't straightforwardly influence income, they give insight into future money commitments. For instance, DTLs signal impending duty instalments, supporting income arrangement and liquidity on the board.Regulatory Changes: Duty regulation corrections, such as changes in corporate assessment rates, can influence the valuation of conceded charge things.Uncertainty in Realization: DTAs depend on the business's ability to generate future taxable income, which can be uncertain.Complexity in Accounting Standards: Navigating differing standards, such as U.S. GAAP or IFRS, adds complexity to deferred tax accounting.